

US money update: more strength
The US composite PMI output index surged to a four-plus-year high in August, according to flash results released last week – see chart 1.
Chart 1
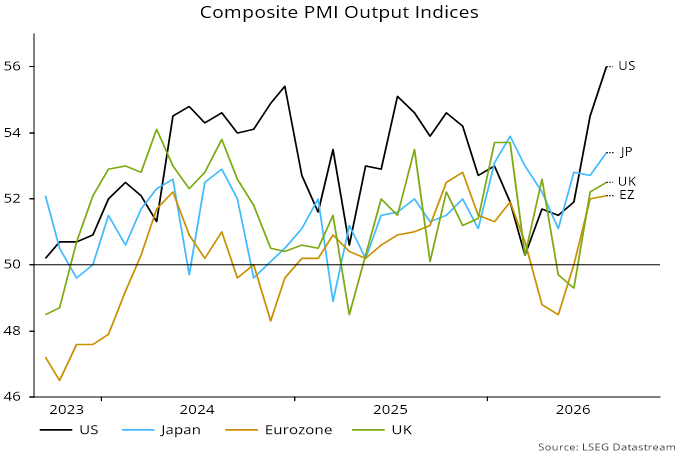
The pick-up is consistent with marked monetary acceleration since the start of the year, which continued last month. Six-month growth of the broad “M2+” measure calculated here reached 8.1% annualised in July, with expansion of narrow money M1A hitting 10.2% – chart 2*.
Chart 2
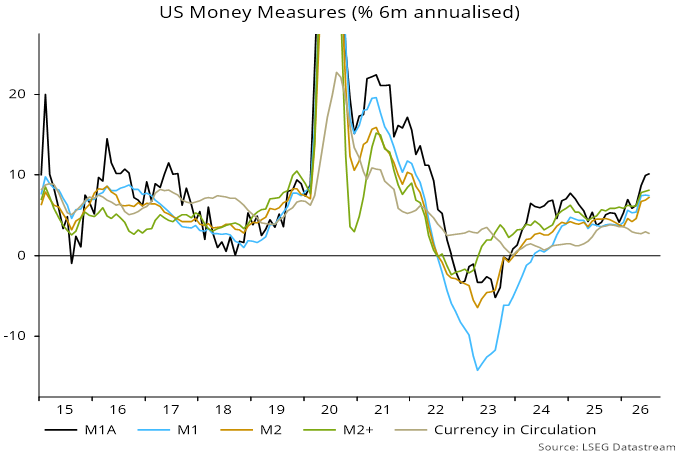
The rise in broad money growth appears to have been driven a combination of firmer commercial bank credit expansion, the Fed’s reserve management securities purchases and external monetary inflows, reflecting large-scale foreign buying of US equities.
Monetary strength suggests that near-term economic news will remain robust, while medium-term inflation risks (i.e. for 2028 and beyond) are rising.
Could money momentum be peaking? Three-month growth of commercial bank loans and leases has fallen since April, although the impact on overall credit expansion has been softened by a pick-up in securities purchases – chart 3. The slowdown has been focused on C&I loans and the “all other” category, which includes lending to non-bank financial institutions.
Chart 3
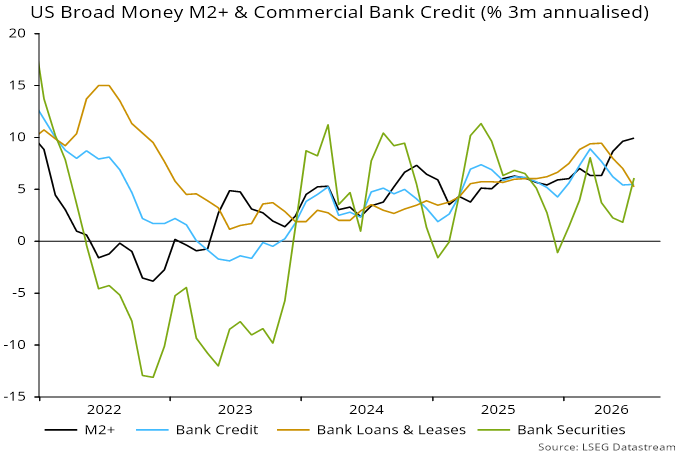
Additionally, the boost from Fed bill buying is moderating, with purchases suspended for the current operating period (ending 14 September) and uncertain prospects for a subsequent resumption at the previous $10 billion per month pace.
*M1A = currency in circulation + demand deposits. M2+ = M2 + large time deposits at commercial banks + institutional money funds.