

Global money update: US lift
Global six-month real narrow money growth recovered further in June but remains below a February peak, as well as its long-term average – see chart 1.
Chart 1
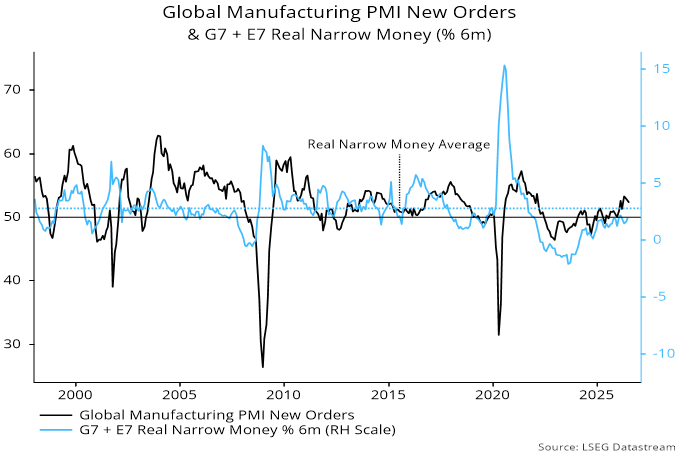
The earlier slowdown suggested that the global industrial economy would lose some momentum during H2. A cooling may already have begun, with manufacturing PMI new orders easing for a third successive month in July. Still, the latest uptick in real money growth argues against significant weakness, at least through year-end.
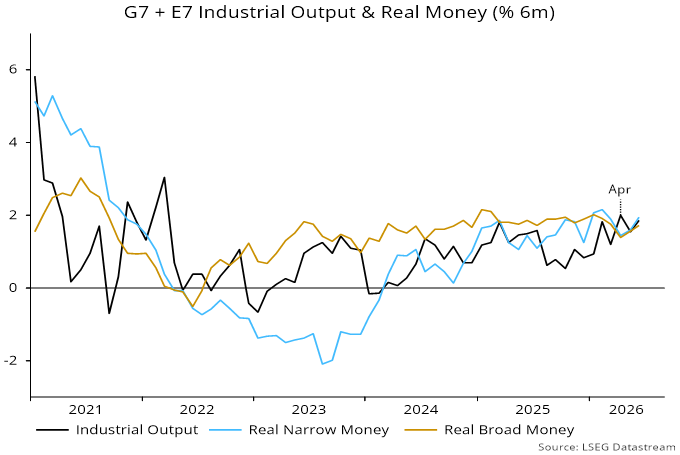
The recent violent correction in momentum stocks followed global six-month real money growth – on both narrow and broad definitions – crossing below industrial output expansion in April, suggesting a loss of “excess” money support for markets. Real narrow money growth reconverged with output expansion in May / June, with real broad money growth slightly weaker – chart 2. This suggests a neutral monetary backdrop for markets, in contrast to positive conditions in late 2025 / early 2026.
Chart 2
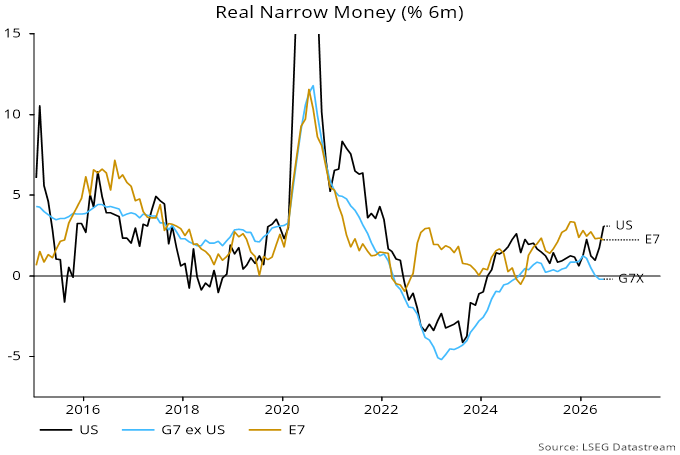
The rise in real money growth has been driven by US acceleration / strength, contrasting with weakness in the rest of the G7 – chart 3. Such divergence is unhealthy, suggesting a misalignment of policy stances, a correction of which could lead to further monetary / market volatility.
Chart 3
Isn’t US real money growth just an artefact of their inflation calculations? That is, health insurance and computing inflation, the main drivers in this cycle, aren’t in the data properly. Wallet inflation is divorced from the official data.
Certainly both payroll surveys and bankruptcy data are inconsistent with strong real money growth presently.
Any such inflation understatement is likely to be small relative to the pick-up in nominal money growth. Real money is a leading indicator so it’s premature to claim an inconsistency with payrolls (coincident) and bankruptcies (lagging)>