

Is China bottoming?
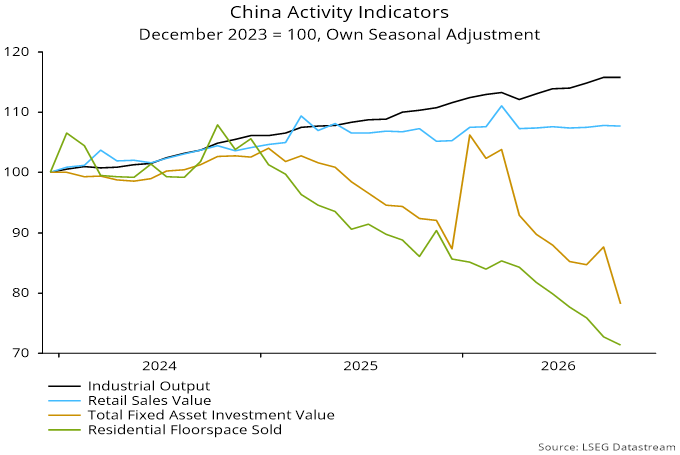
Chinese October activity numbers were worryingly weak, with industrial output / retail sales flatlining and fixed asset investment / home sales falling further – see chart 1.
Chart 1
Monetary trends, however, offer a glimmer of hope. Six-month growth of real narrow money extended a recent recovery last month – chart 2.
Chart 2
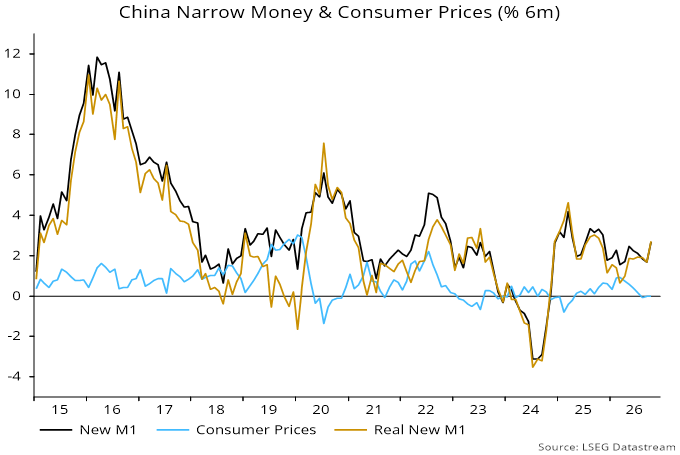
The inclination here is to play down this improvement, for three reasons. First, the recovery partly reflects a fall in six-month consumer price momentum, which may prove temporary – chart 2.
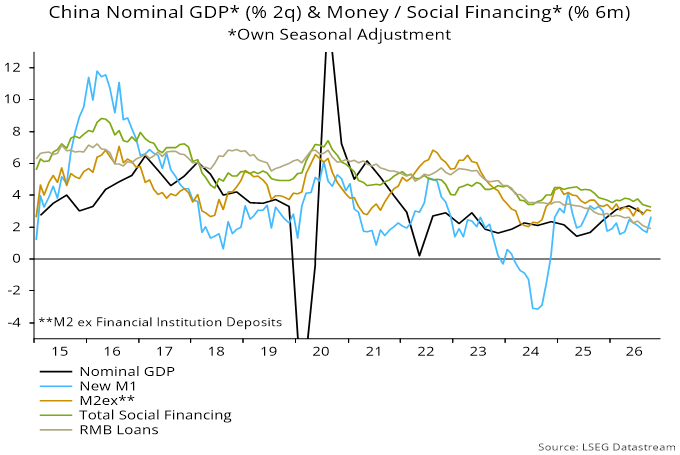
Secondly, stronger nominal narrow money growth has not been accompanied by a pick-up in expansion of the broad money measure tracked here, while credit aggregates continue to slow – chart 3.
Chart 3
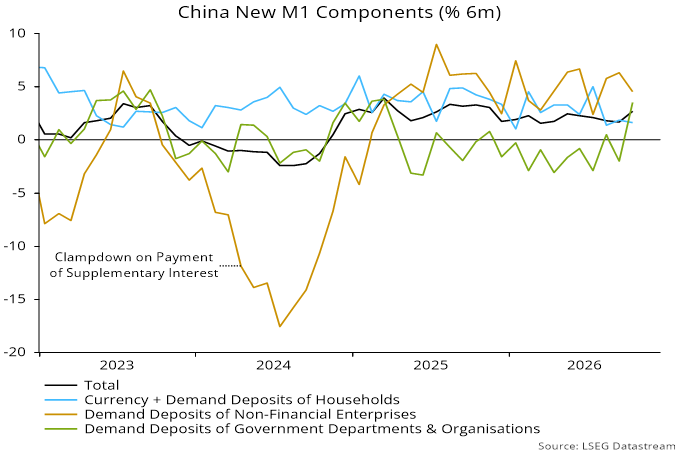
Thirdly, the rise in narrow money growth has been driven by increased demand deposit holdings of government-related bodies, with expansion of household and non-enterprise deposits little changed – chart 4. This is consistent with fiscal funds being deployed to ensure that the 2026 GDP growth target of 4.5% is achieved, raising the possibility of an unwind in early 2027.
Chart 4
Still, a further pick-up in narrow money growth into year-end would warrant a positive reassessment.